The Government’s new Your First Home scheme needs safeguards to prevent taxpayer support being absorbed into new-build prices and leave buyers with homes that struggle to grow in value, a leasehold expert has warned.
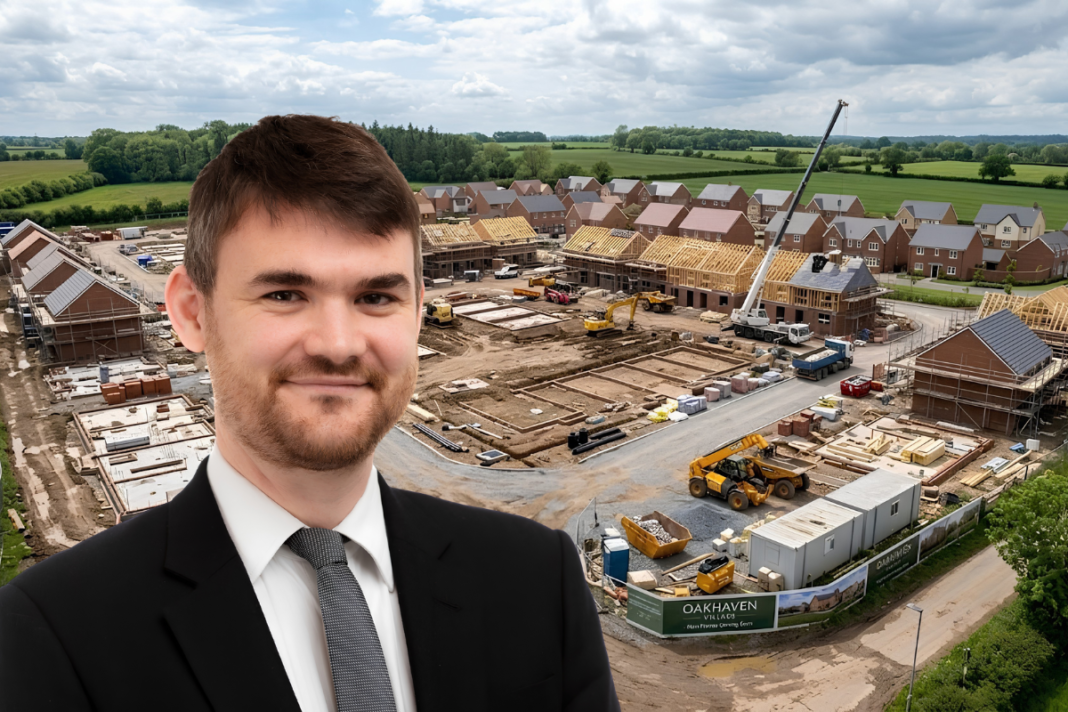
Linz Darlington (main picture, inset), Managing Director of lease extension specialist Homehold, says lessons should be learned from the former Help to Buy equity loan scheme as the Treasury prepares to reveal full details of its replacement at the Autumn Budget.
Your First Home will offer first-time buyers purchasing qualifying new-build properties in England access to a 20% government-backed equity loan alongside a deposit of 2.5%.
The Government has already confirmed that household income and local property price caps will apply, while participating developers will be expected to make a contribution towards the cost of the scheme. Full details, including the caps, costs and implementation timetable, are due at the Budget.
HELP TO BUY LESSONS
Darlington says: “Getting on the housing ladder is the aspiration of many. But for that first rung to be valuable, the homes available need to be fairly priced and have a reasonable chance of growing in line with the wider market.
“Labour’s ‘Your First Home’ scheme risks repeating the flaws of Help to Buy if it channels taxpayer support into new-build developments without enough safeguards on price.”
A National Audit Office review of Help to Buy found the scheme increased homeownership and housing supply, but also raised questions over how targeted the support was.
Around three-fifths of recipients could have bought a property without Help to Buy, although not necessarily the property they wanted, while 37% said they could not have bought at all without the scheme.
The NAO also found five of England’s largest developers had increased the number of properties they sold and their annual profits following the scheme’s introduction. In 2018, between 36% and 48% of those developers’ sales were supported by Help to Buy.
Darlington adds: “Income and price caps are a step forward, but a cap limits what a buyer can purchase. It doesn’t stop developers pricing up to it.”
FLAT PRICE GAP
His warning comes amid a widening divide between the performance of houses and flats.
Zoopla analysis shows the average UK house costs £327,000 compared with £193,000 for a flat – a ratio of 1.7 to one and the widest gap in 30 years.
House prices have increased 43% since 2016, while flat values have risen just 10%. Zoopla also found four in five flats listed for sale in England are leasehold, with typical ground rent and service charges totalling around £2,100 a year.
Darlington says: “First-time buyers, particularly in London, often buy flats, taking on significant borrowing against assets that have seen sluggish price growth. Leaseholders also face unpredictable service charges, poor management and building safety problems.”
The Government is already pursuing wider leasehold reform. In July it confirmed plans to strengthen transparency around service charges and said further legislation would form part of its move towards commonhold becoming the default tenure.
BUDGET SAFEGUARDS
Darlington adds: “If the Treasury wants to help first-time buyers, the Budget should ensure support isn’t swallowed up by inflated developer margins.
“It should also make sure the homes bought are not weighed down by the leasehold problems the Government has promised to fix.
“Without that, these homes risk becoming trapdoors rather than genuine long-term investments.”