Shares in Britain’s biggest housebuilders surged by as much as 15% on Monday as investors reacted to the Government’s new Your First Home scheme for first-time buyers.
Persimmon climbed around 15% by early afternoon, while Barratt Redrow and Taylor Wimpey were around 12% higher, Vistry gained 10% and Crest Nicholson rose 8.5%.
The rally followed the Government’s announcement that Your First Home is expected to allow eligible first-time buyers in England to purchase new-build properties with deposits starting at 2.5%, supported by a government-backed equity loan worth 20% of the purchase price.
The equity loan will have an initial interest-free period, while household income and local property price caps will be used to target the scheme.
HOUSEBUILDER RALLY
Full details, including costs and the implementation timetable, are due to be announced at the Budget next month.
The Government says the scheme is intended both to tackle the deposit barrier facing first-time buyers and stimulate a new-build market facing challenging economic conditions and rising construction costs.
Developers participating in Your First Home will also be expected to make a financial contribution towards the scheme, although the level has yet to be disclosed.
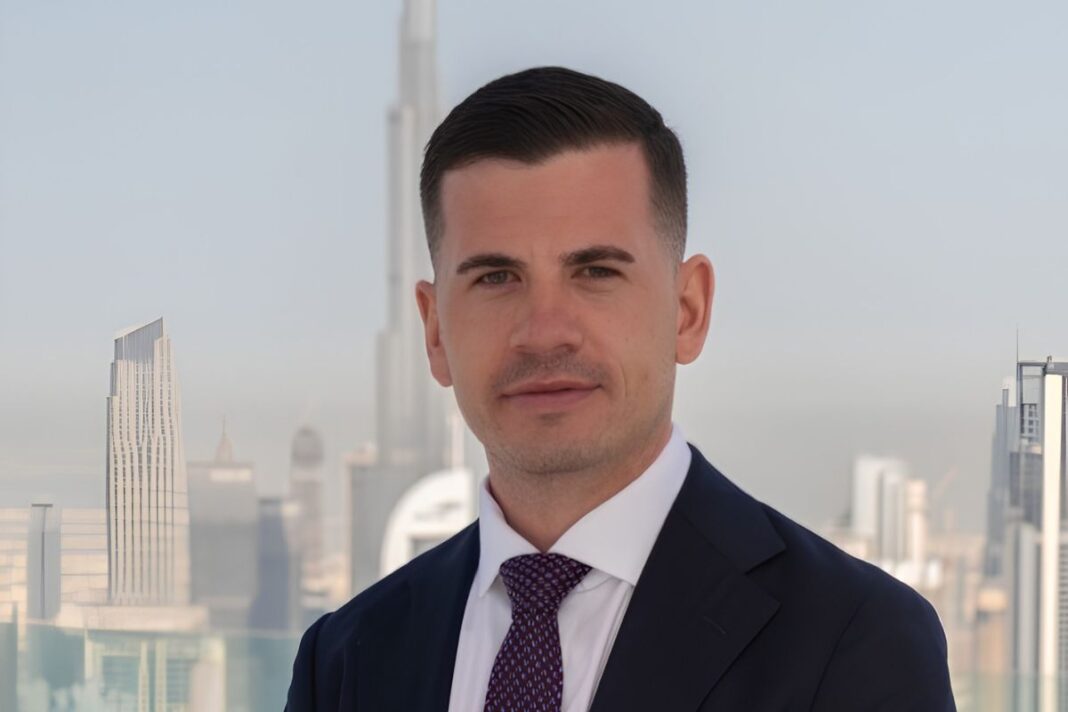
But James Bentley (main picture), Director of Financial Markets Online, warns investors against assuming the new scheme will recreate the impact of Help to Buy.
He says: “Anyone betting on another Help to Buy-fuelled gold rush could get badly burnt once this 2026 reboot gets off the drawing board.
“The similarities between the two schemes have triggered a double-digit jump in the shares of Britain’s big housebuilders.
“But the froth says more about the desperation of investors for any good news after a miserable year for the sector, rather than the likelihood of a new housebuilding bonanza.”
MORTGAGE PRESSURE
One significant difference between the launch of Help to Buy in 2013 and today’s market is the cost of borrowing.
Bank Rate currently stands at 3.75%, compared with 0.5% throughout 2013.
The Bank of England’s Monetary Policy Committee voted 6–3 this month to leave Bank Rate unchanged, with three members supporting an increase to 4%.
Its September survey of market participants, conducted before the latest MPC meeting, put the median expectation for November at 3.75%. Respondents assigned an average 35% probability to Bank Rate being at 4% after that meeting.
However, the rate outlook has since hardened. At a Bank of England Market Participants Group meeting on 24 September, participants agreed that the economic outlook and MPC communications were consistent with expectations that Bank Rate may need to rise.
The Bank also says quoted two-year fixed mortgage rates are around 0.95 percentage points higher than before the Middle East conflict, following increases in market interest rates.
Bentley says: “Helping would-be buyers get a mortgage is one thing, but making them want one when interest payments are so high is another.”
NEW-BUILD MARKET
The latest official house price figures also highlight the premium attached to new-build properties nationally.
The latest reliable UK House Price Index breakdown puts the average new-build property in England at £381,000 in May, compared with £288,000 for an existing resold home.
However, the position varies considerably by location. In London, the average new-build property was £509,334 in May compared with £549,723 for an existing property.
Official figures also show continued weakness in the flats market. The average flat or maisonette in England was worth £219,000 in June, down 2.3% annually, while overall English property prices increased 1.8%.
Bentley says: “Few industries rely on confidence more than construction, but this dizzy surge in valuations is built on sand rather than concrete.”
DEMAND BOOST
Emeritus Professor Joe Nellis, Head of Economic Research at accountancy and advisory firm MHA, takes a more positive view, arguing the scheme could provide a “much-needed shot in the arm” for the housing market.
He says: “The new scheme should help unlock some of the pent-up demand from aspiring homeowners who are able to afford a mortgage but struggle to raise an adequate deposit.
“Reducing the required deposit to just 2.5%, alongside a 20% government equity loan, will significantly lower the biggest upfront barrier facing many first-time buyers. It could also boost confidence quickly, encouraging potential buyers who have been sitting on the fence to make the final decision to buy.”
Nellis says stronger new-build demand could also benefit housebuilders and generate more transactions across the wider property market.
But he warns that increasing buyers’ purchasing power without a corresponding increase in housing supply could have unintended consequences.
He adds: “Britain does not simply have an affordability problem; it has a chronic housing supply problem. Boosting buyers’ purchasing power without delivering substantially more homes risks translating government support into higher prices.
“This initiative has the potential to stimulate buyer confidence just when it is most needed. But only time will tell if the scheme creates more homeowners and more homes — or just even more expensive homes.”