The Government is being urged to allow first-time buyers to use its new 2.5% deposit scheme to purchase secondhand properties rather than restricting it to new-build homes.
SAM Conveyancing argues that extending Your First Home across the existing housing market could help unlock property chains by enabling first-time buyers to purchase homes from existing owners looking to move up the ladder.
The Government confirmed last week that Your First Home will provide eligible first-time buyers in England with government-backed equity loans worth 20% of the purchase price alongside deposits expected to start at 2.5%.
Under the plans currently announced, however, the scheme will be restricted to new-build properties purchased from participating developers, with further details due at the Budget on 28 October.
SECONDHAND HOMES
SAM Conveyancing wants Chancellor John Healey to widen the scheme to existing properties, with any government equity stake based on an independent RICS-regulated valuation.
It argues this would spread the benefits beyond housebuilders and potentially allow first-time buyer purchases to trigger transactions further up the property chain.
The firm bases its argument partly on the experience of Help to Buy, which ran from 2013 until 2023 and was also focused on new-build properties.
Official figures show 387,195 homes were purchased using a Help to Buy equity loan, including 328,346 by first-time buyers. The loans had a combined value of £24.7bn and supported property purchases worth £109.2bn.
SAM’s analysis of Land Registry figures finds the average price of a new-build property increased from £208,086 when Help to Buy launched in April 2013 to £353,867 when it closed in March 2023.
The firm argues that restricting government equity support to new homes contributed to higher new-build prices. The price increase alone, however, does not establish that Help to Buy caused the rise.
NEW-BUILD PREMIUM
SAM says its analysis puts the average new-build price at £396,889 by May 2026, compared with £283,194 for an existing property — a premium of around 40%.
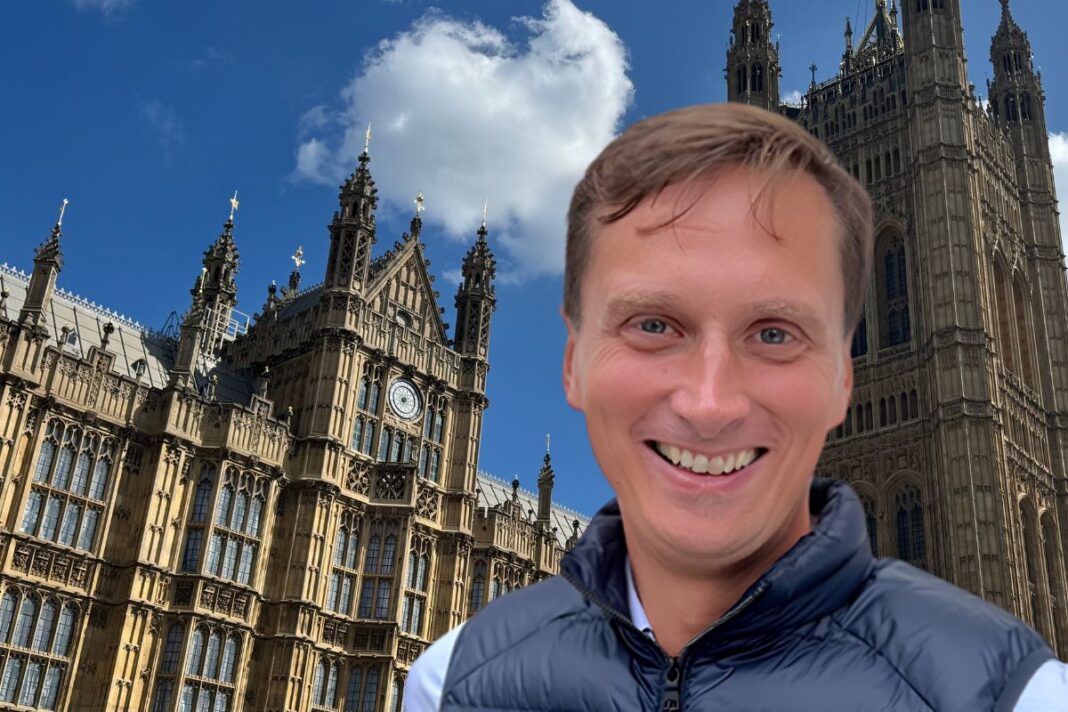
Andrew Boast (main picture, inset), Chief Executive of SAM Conveyancing, says: “Repeating this policy by restricting the incoming ‘Your First Home’ scheme solely to new developments will not magically double our construction capacity overnight. It will simply pump billions in state support into developer balance sheets, leaving buyers to absorb an immediate 40% price premium.”
The Government takes a different view of the role of the new scheme, saying Your First Home will help overcome the deposit barrier while providing stimulus to a new-build market facing higher construction costs and other economic pressures.
PROPERTY CHAINS
Boast argues allowing the equity loan to be used for existing homes would have a wider effect on transaction volumes.
He says: “Thousands of existing homeowners are stuck in starter properties because incoming buyers struggle to raise conventional deposits. Opening the equity loan to existing properties allows first-time buyers to purchase established homes, freeing current owners to step up to larger properties and restoring natural fluidity across the entire chain.
“Finally, to protect the public purse and ensure sellers cannot artificially inflate asking prices, equity loans on secondhand homes should be strictly pegged to an independent valuation from a RICS-regulated surveyor at the point of purchase.”
He adds: “If Chancellor John Healey genuinely wants to get Britain moving, he should let first-time buyers use this scheme on any property they choose.”