Annual UK house price growth halved in September as higher borrowing costs and economic uncertainty continued to weigh on the property market.
Prices increased by 0.8% year-on-year, down from 1.6% in August and the weakest annual growth since December 2025, according to the latest Nationwide House Price Index.
On a seasonally adjusted basis, prices fell 0.2% during September, reversing August’s 0.2% increase.
The average UK property price stood at £274,251 on the lender’s monthly measure, down from £275,465 in August.
MORTGAGE PRESSURE
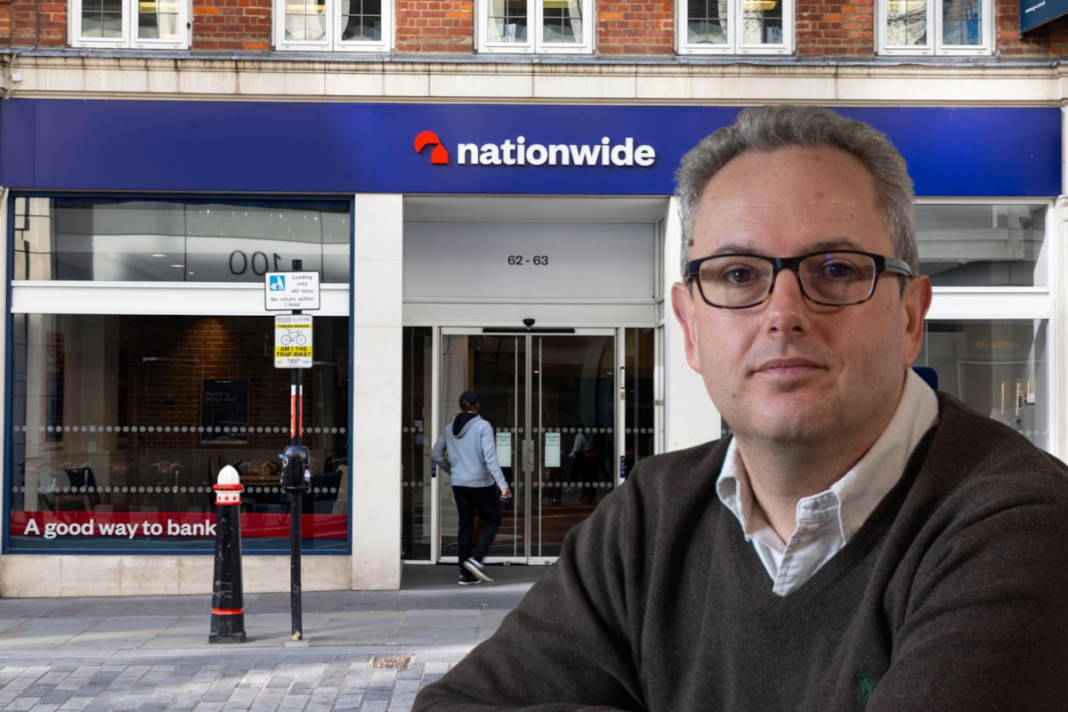
Robert Gardner (main picture, inset), Chief Economist at Nationwide, says market activity and house prices have remained subdued amid the uncertain economic backdrop and pressure on mortgage pricing.
He says: “Geopolitical tensions remain high, with the conflict in the Middle East exerting upward pressure on energy prices, fanning inflation concerns.
“This in turn has led to mounting financial market expectations of Bank Rate increases, which has maintained upward pressure on the market interest rates which underpin mortgage pricing.”
However, Gardner says underlying affordability has been improving because earnings have been rising more quickly than house prices.
He adds: “These gains have been only partially offset by higher mortgage rates. This suggests that activity should regain momentum in the quarters ahead providing the energy shock fades and confidence returns – especially if market interest rates fall back to pre-conflict levels.”
NORTH-SOUTH DIVIDE
Nationwide’s quarterly figures reveal an increasingly pronounced regional divide.
Average prices across southern England fell 0.1% year-on-year during the third quarter, with London the only southern region recording growth, at 0.4%.
East Anglia is the weakest-performing UK region, with prices down 0.7%, followed by the East Midlands at 0.5% and South West at 0.3%.
By contrast, prices across northern England increased by an average 1.6%.
The North West remains England’s strongest-performing region with annual growth of 3.9%, while Northern Ireland leads the UK with prices up 5.9%.
Scotland recorded growth of 3.3%, while Wales slowed sharply from 3.5% in the second quarter to 0.7%.
FLATS LAG
Price growth has also slowed across every property type.
Terraced homes performed strongest during the third quarter, recording annual growth of 1.8%, while flat prices were essentially unchanged from a year earlier.
The longer-term gap is more pronounced.
Nationwide says the price of a typical flat has risen 14% since the beginning of 2020, less than half the 31% increase recorded by semi-detached homes over the same period.
It says this partly reflects weaker performance in London, where flats account for a much larger proportion of the housing stock.
INDUSTRY REACTION|: AFFORDABILITY PRESSURES DRIVE CAUTION
Nathan Emerson, Chief Executive Officer at Propertymark, says: “As the economy continues to face uncertainty and fluctuation, it is unsurprising that the effects are increasingly being felt across the housing market.
“Many consumers are taking a more cautious approach to their finances, with affordability pressures continuing to influence decisions around buying and selling.
“With the Autumn Budget only weeks away, there will be close attention on whether the UK Government introduces measures that provide greater certainty for buyers and sellers.
“Support to help first-time buyers overcome barriers to homeownership would be particularly welcome, while measures that encourage investment in housing will also be important to ensure the market can meet future demand.”
PRICE SENSITIVITY COMES TO THE FORE
Jason Tebb, President of OnTheMarket, says: “The dip in annual house price growth suggests increased price sensitivity as focused, needs-based buyers and sellers return from the summer determined to move before the end of the year.
“National averages conceal significant local variations depending on the type of property and where it is located, making the guidance of a knowledgeable local agent particularly valuable.
“Market resilience is still evident, despite higher mortgage costs sounding a note of caution. The Bank of England’s decision to hold interest rates so far this year has helped affordability, but there are fears rising energy bills may force its hand this autumn depending on inflation risks.
“All eyes will be on the Budget later this month. We already know there will be assistance for first-time buyers purchasing new-build homes and hope the Budget provides some much-needed impetus for the housing market and wider economy.”
MORTGAGE RATES TAKE TOLL ON DEMAND
Tom Bill, Head of UK Residential Research at Knight Frank, says: “House prices are stalling as rising mortgage rates take their toll on demand, a pattern we expect to continue in the final three months of this year.
“Mortgage approvals fell 14% against the five-year average in August, which means transaction numbers will also increasingly feel the squeeze.
“The outlook beyond 2026 depends on how the unpredictable Middle East conflict unfolds and what property-related measures Chancellor John Healey announces in the Budget.”
AUTUMN MARKET FACES AFFORDABILITY TEST
Iain McKenzie, Chief Executive Officer of The Guild of Property Professionals, says: “September’s slowdown in house price growth to 0.8% is another indication that economic headwinds are continuing to put the brakes on the market.
“Autumn normally provides a natural boost to activity, but elevated borrowing costs are making that recovery more difficult.
“Swap rates have risen and some lenders have responded by increasing mortgage rates, putting further pressure on purchasing power. Net mortgage approvals for house purchase also fell to 54,900 in August, below the previous six-month average.
“That said, there are encouraging signs beneath the headline figures. Home searches are 7% higher than a year ago, suggesting buyers are re-engaging even if some are not yet ready to commit.
“With inflation still elevated and borrowing costs weighing on affordability, more buyers and sellers may choose to sit tight.
“The autumn market is therefore likely to be characterised by genuine demand but also a high degree of caution, with affordability and pricing determining whether interest translates into transactions.”
BUYERS NEGOTIATE HARDER
Jeremy Leaf, North London estate agent and former RICS Residential Chairman, says: “Higher borrowing costs and inflation, as well as plenty of choice with the prospect of more to come, are compromising confidence in an already-nervous market. That is to say nothing of the impact of the Budget as the date looms larger.
“The result is buyers negotiating harder, especially for flats, to build in sufficient headroom to weather any further financial storms.
“The good news is demand has slowly improved over the past three to four weeks, so we expect more activity looking forward, although already protracted transactions are unlikely to shorten any time soon.”
SELLERS FACE TEST OF REALISM
Jonathan Hopper, Chief Executive Officer of Garrington Property Finders, says: “A stagnant summer has been followed by a September slide in prices. Such a sharp slowdown in the annual pace of growth cannot be dismissed as one bad month.
“Large parts of the UK property market are stuck in a rut, with the number of homes for sale exceeding the number of serious buyers. This is applying downward pressure to prices, and no longer just in the South East.
“Across England as a whole, average prices fell 0.7% in Q3 compared with the previous three months, while prices in Wales fell 1.4%.
“Nevertheless, there are some positive signs for London. After months of sliding prices, it has given up its position at the bottom of the regional table. Prices in the capital posted annual growth of 0.4%, placing it above the rest of southern England and the East Midlands.
“Buyer sentiment remains fragile in many areas, with prices in the South being squeezed disproportionately hard. High property values mean many buyers need larger mortgages, and rising interest rates have reduced the amount they can afford to borrow.
“Bank of England data showed home purchase mortgage approvals in August were down 9% compared with the monthly average over the previous six months, suggesting the pipeline of buyers is slowing.
“The buyers who are out there are therefore spoilt for choice and making the most of their negotiating position. With a surplus of homes for sale in London and the South East, financially prepared buyers can often secure sizeable discounts from asking prices.
“September traditionally brings a ‘back to school’ bounce in buyer numbers, but things are more muted than usual this year and autumn will be an important test of seller realism. In a market like this, yesterday’s asking price can quickly become tomorrow’s unsold property.
“For financially secure buyers, that shift in psychology may ultimately prove more important than the headline movement in the index itself.”
CORRECTLY PRICED HOMES ARE SELLING
Amy Reynolds, Head of Sales at Antony Roberts, says: “We’re seeing a sensible, needs-driven market: well-presented homes priced correctly are selling, while those pitched too hopefully are sitting.
“The Nationwide figures are not surprising as we expect a quieter-than-usual September and October for new stock as people ‘wait and see’ ahead of the Budget.
“However, stamp duty isn’t likely to change on 28 October, so there’s little to be gained by holding off, and every week you stall is another week for a chain to wobble. We would always advise exchanging when your paperwork is ready, not when the Chancellor sits down.
“Lenders haven’t waited for the Bank of England to move interest rates, with mortgage pricing edging upwards. With inflation above target, we expect rates to hold rather than fall this side of Christmas. That isn’t a crisis, but it does mean buyers waiting for a cheaper mortgage to rescue their budget could be waiting a long time.
“Overall, we’re hoping for a post-Budget bounce and a busy December setting us up well for 2027.”
OVERPRICING RISKS LEAVING SELLERS BEHIND
Nicky Stevenson, Managing Director of Fine & Country, says: “Nationwide’s latest figures underline how finely balanced the housing market remains. Buyers have more choice, which means competition between sellers is particularly strong.
“While autumn typically brings a fresh wave of activity as people return to their routines and revisit moving plans, many buyers are still sitting tight. There are signs of re-engagement, with home searches 7% higher than a year ago, but buyers remain cautious and have little reason to overpay when there is so much choice.
“Late August and early September often bring a fresh round of asking-price reductions as sellers recalibrate, and this year that adjustment looks particularly important.
“Sellers who price realistically from day one will be best placed to convert renewed interest into viewings and offers. In a market where buyers can afford to be selective, overpricing risks leaving a property behind the competition rather than creating the momentum sellers are looking for.”