Estate agents have been warned that fragmented anti-money laundering and client due diligence processes could leave compliance gaps hidden across their businesses.
Client due diligence platform Thirdfort says property firms increasingly use digital identity, onboarding and AML technology but may still operate multiple systems and processes that have been added over time.
The result can be different parts of the business carrying out due diligence in different ways, making it harder for compliance teams to maintain oversight of risks across an organisation.
Thirdfort warns this could expose regulated property businesses to regulatory investigations and potential penalties while increasing the administrative burden on compliance teams.
FRAGMENTED PROCESSES
Estate agents, conveyancers and law firms are required to balance increasingly demanding compliance obligations with the need to onboard clients efficiently.
Thirdfort argues that using several tools and manual workarounds rather than a consistent due diligence process can make that more difficult.
Olly Thornton-Berry, Co-Founder and Chief Executive Officer of Thirdfort, says: “Compliance professionals in property firms are dedicated and hardworking professionals. They face increasing expectations from regulators and clients alike.
“Yet many are dealing with fragmented processes that create additional administration and may conceal firmwide risks.
“That’s why we’re highlighting the risks of such processes and making the case for client due diligence that puts compliance professionals in control.”
AML PRESSURE
Thirdfort says millions of people are now verified through digital onboarding processes, but technology does not remove the need for firms to maintain clear oversight of their compliance procedures.
Its warning forms part of a new campaign highlighting the pressures faced by senior compliance professionals and the potential risks created by workaround processes.
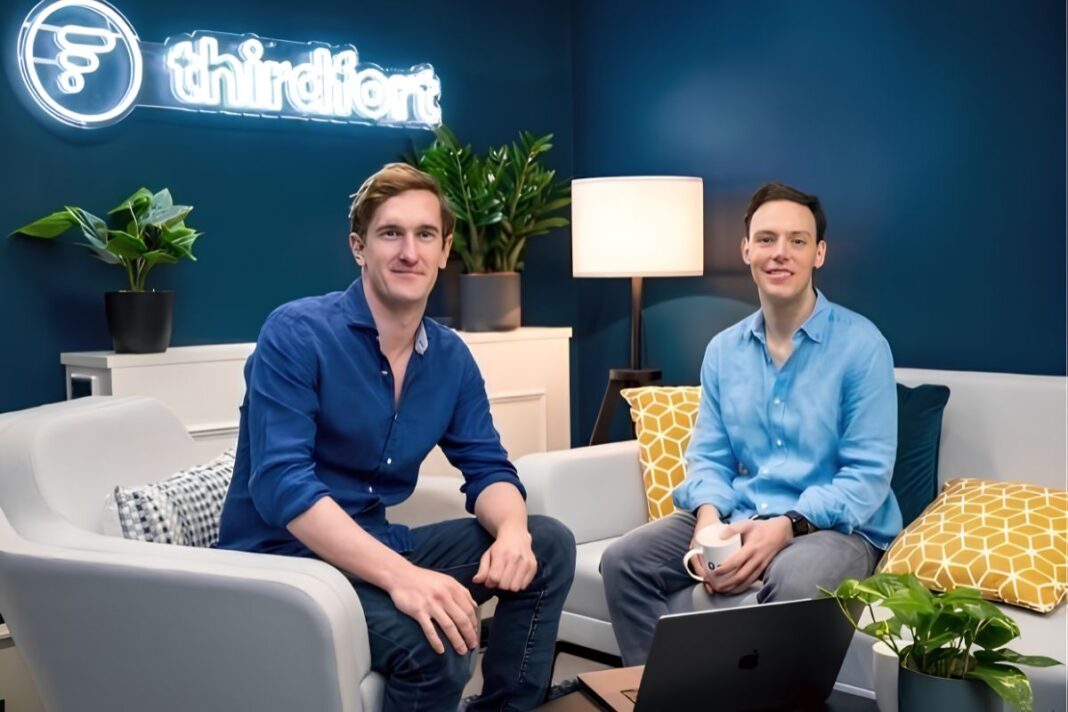
Main picture: Thirdfort co-founders Jack Bidgood and Olly Thornton-Berry.