Property sales agreed have fallen year-on-year for four consecutive months as the number of homes coming to market reaches a 10-year high, new data reveals.
TwentyCi figures show sales agreed were around 8% lower than a year earlier in both May and June, followed by declines of 5% in July and 6% in August.
Across the first eight months of 2026, the number of sales agreed is 5.4% below the equivalent period last year.
At the same time, new property listings are 2.1% higher year-on-year and have reached their highest level for a decade, increasing competition between sellers and giving buyers greater choice.
WEAKER PIPELINE
The decline in sales agreed contrasts with completed transaction figures, which continue to reflect deals negotiated earlier in the year.
HMRC recorded residential transactions 5% higher year-on-year in July, although transaction numbers remain 2.5% lower across the year to date.
TwentyCi argues its more timely sales agreed figures point towards a weaker pipeline of transactions feeding through during the final quarter.
It forecasts 1.16 million residential transactions during 2026, 3.9% fewer than the 1.21 million recorded in 2025 but still 5.6% above 2024.
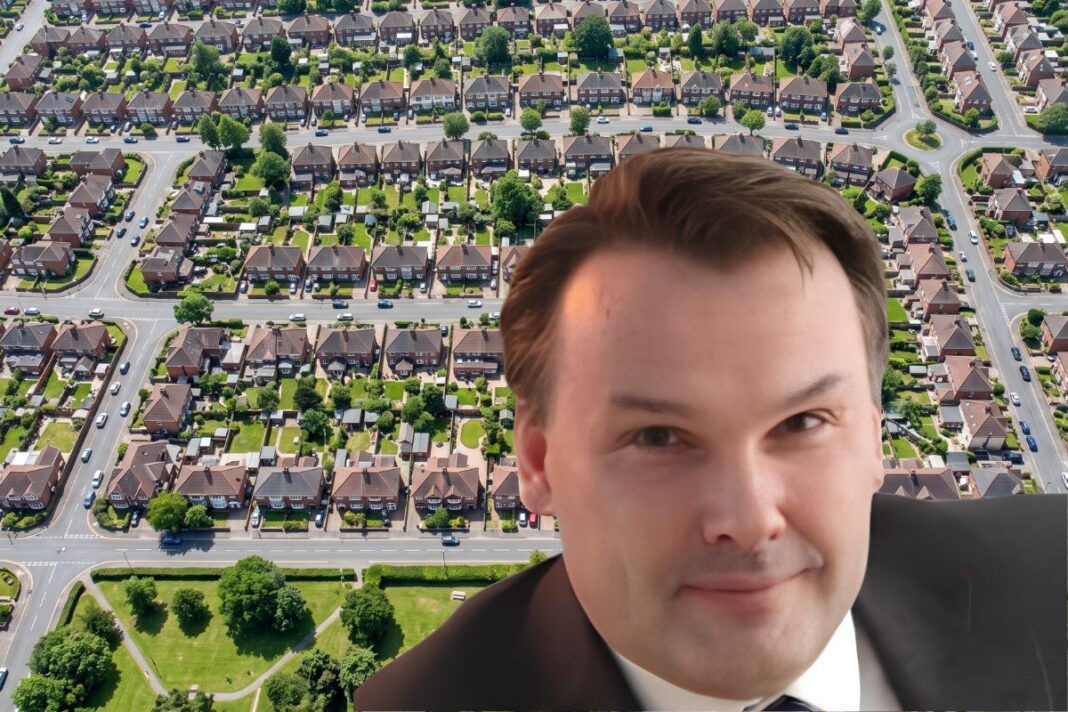
Colin Bradshaw (main picture, inset), CEO of TwentyCi, says: “The housing market is presenting something of a mixed picture. On the surface, the latest transaction figures suggest that activity remains relatively resilient, but when we look at the more timely sales agreed data, a different story is emerging.
“Buyer demand has fallen by more than 5% year-on-year in every month since May, and that sustained weakness will inevitably feed through into completed transactions with a lag.”
BUYERS GAIN GROUND
The combination of more properties for sale and fewer sales being agreed is shifting the balance of the market towards buyers.
TwentyCi says its demand-to-supply ratio has deteriorated across every major property type, with flats recording the largest year-on-year decline at 13.2%.
Affordability could also face renewed pressure from rising swap rates, which have prompted some mortgage lenders to increase fixed rates despite no change in Bank Rate.
Bradshaw adds: “The renewed rise in swap rates adds another layer of uncertainty. If fixed mortgage pricing continues to move upwards, it could put further pressure on affordability and make buyers even more cautious at a time when demand is already subdued.”